

Walmart MoneyCard®

- 1.88K Reviews
- 3.7
- Downloads
- 500,000+
Our take on Walmart MoneyCard® from Appgk
I approached Walmart MoneyCard® as a practical finance app rather than a full replacement for every banking tool. Its main appeal is straightforward: it gives people a mobile place to manage a Walmart MoneyCard account, check what is happening with their money, and keep everyday spending visible. That sounds simple, but simplicity matters when the person using the account is trying to coordinate groceries, household purchases, or a regular spending allowance without opening a complicated banking dashboard.
The app is free to install, comes from Green Dot, and sits in the finance category. Its store summary, “Bank better with our new app,” is broad, so I found the real question is not whether it looks like a complete bank, but whether it fits the way you already use a Walmart MoneyCard. In my experience, it makes the most sense as a focused companion for card management. It is less convincing if you expect a traditional checking account, detailed household budgeting, or a shared family workspace.
How it fits a shared household routine
A realistic example is a household where one person handles the main grocery trip while another person needs a clear view of the available balance before buying fuel or household supplies. In that situation, the app can be useful because the cardholder can check the account from a phone instead of relying on memory or waiting to review a paper receipt. I like this kind of narrow usefulness: it turns a quick money check into a habit that can happen before a purchase, not after a budget has already been disturbed.
There is an important boundary, though. I would not treat the app as a shared-device wallet where everyone in the home should remain signed in. A finance app is tied to account access, so sharing a phone or handing the device to another person changes the privacy risk. The better arrangement is for each cardholder to use their own device and manage their own sign-in. If one household member only needs to know whether a purchase is affordable, I would share the amount or spending plan verbally rather than handing over unrestricted account access.
Best Parts of Walmart MoneyCard®
Things to Keep in Mind About Walmart MoneyCard®
This distinction is especially important for couples, roommates, and parents coordinating expenses. The app may help one person stay informed about their own card, but that is not the same as providing a household ledger. I would still use a separate shared note or budgeting method for rent, utilities, subscriptions, and reimbursements. Keeping those responsibilities outside the card app prevents a common mistake: assuming that seeing one card balance means seeing the complete financial position of the household.
For a personal spending routine, the focused design is an advantage. I can imagine opening it before leaving for the store, checking the available money, completing the purchase, and reviewing the account later to make sure the activity makes sense. That workflow is more useful than a collection of advanced charts if the immediate goal is simply avoiding an unpleasant surprise at checkout.
News and Features Related to Walmart MoneyCard®

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What I would do before handing over a phone
If another person needs to use the phone for navigation, shopping, or any unrelated task, I would sign out of the finance app first and use the phone’s normal privacy protections. I would also avoid saving account details in a place that other household members can casually see. These are not special Walmart MoneyCard® controls; they are sensible boundaries around any financial application, and they matter more when a device moves between several people.
I would also establish one simple rule: the account holder checks the balance and transaction activity personally. A partner or roommate can help with planning, but the person whose money is involved should be the one to confirm activity. That reduces confusion when several purchases happen close together and avoids treating a shared household arrangement as if it were a formally shared account.
Don't want to read the full review?
The app is available for devices running Android 9 or later, which makes it accessible to people who are not using the newest phone. Still, compatibility is only one part of a smooth setup. A phone that is shared, unlocked, or used by several people deserves extra care because the practical weakness may come from the device routine rather than the application itself.
Setup is simple in concept, but account boundaries matter
My advice is to begin with the person who owns the Walmart MoneyCard account and use that person’s details consistently. Do not create a household login just because several people contribute to groceries or bills. A shared password can make coordination feel easier at first, but it blurs responsibility and makes it harder to know who should respond when an unfamiliar transaction appears.
Screenshots
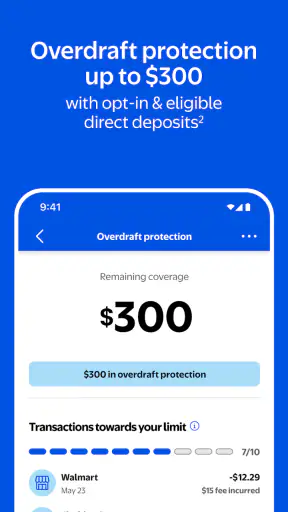
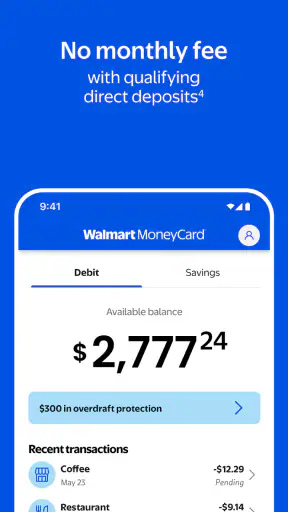
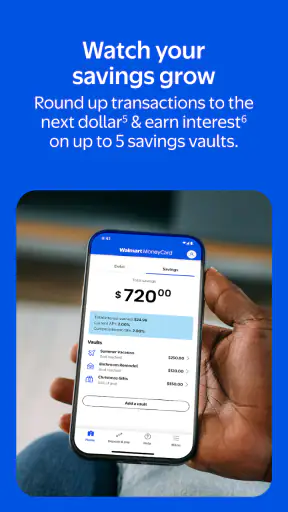
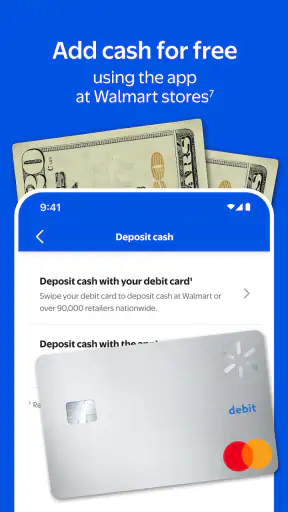
Before relying on the app for an important purchase, I would complete the initial sign-in at home, when there is time to resolve any account or device issue calmly. Then I would open the app again before using it in a checkout line. This small test is useful because a finance app should not be treated like a casual shopping application; you want confidence that you can access the account when you actually need to verify spending.
I would also keep the app’s role clear. It is for managing the Walmart MoneyCard experience, not for merging several outside accounts into one household picture. If your financial life includes a separate bank account, cash expenses, another prepaid card, or shared bills, you still need another way to bring those pieces together. That is a trade-off rather than a flaw: a focused card app can be easier to understand, but it naturally gives you a narrower view.
One useful habit is to separate “balance checking” from “budget planning.” The app can help you see what is available on the card, while a note, spreadsheet, or conversation can record what that money is already meant to cover. For example, a balance may look comfortable until you remember that part of it is reserved for a weekend trip or a utility payment. I would never use the displayed balance as permission to spend the entire amount without considering those commitments.
Coordinating purchases without pretending the app is a family dashboard
For shared errands, I found the most sensible workflow is agreement first, app check second, purchase third. A household can decide that one person will buy groceries, another will cover fuel, and the cardholder will verify the available money before each trip. This creates a clear division of responsibility without requiring everyone to access the account.
That arrangement is particularly helpful for roommates. Instead of giving a roommate access to the app, the cardholder can decide whether a specific purchase fits the plan and then record the reimbursement separately. It may feel less automatic than a dedicated shared budgeting service, but it is safer than turning a personal card login into a communal tool. The app remains the source for the card’s activity, while the roommates’ agreement handles who owes what.
For couples, the best use depends on whether the card is personal or intentionally part of a wider spending plan. If both people need real-time authority over the same money, I would compare this focused card experience with a bank account or budgeting service designed around joint access. If one person simply wants a convenient way to manage their own spending while contributing to the household, Walmart MoneyCard® can be a reasonable fit.
A non-obvious benefit of this separation is that it reduces accidental edits or misunderstandings. The person who owns the account remains responsible for checking activity, while the household conversation deals with plans rather than passwords. In practice, that can be calmer than trying to make one app represent every relationship in the home.
I would also review activity after a shared shopping trip instead of assuming that the amount at checkout tells the whole story. A quick follow-up check can help catch a duplicated purchase, an unexpected charge, or simply a forgotten transaction. This is not a substitute for careful account security, but it is a useful routine for anyone whose card is involved in regular household spending.
Age, trust, and the limits of shared access
The app carries a Mature 17+ content rating, so I would not present it as a child-focused money-learning tool. That age context matters when a family is deciding whether a younger person should handle the phone or participate in card management. A teenager may be involved in a conversation about budgeting, but that does not automatically mean they should receive the account credentials or use an adult’s signed-in device.
For older teens and adults, the app can support a straightforward lesson: check available money, plan the purchase, and review activity afterward. I like that this workflow connects a real card with real spending decisions instead of reducing money management to a game or abstract chart. At the same time, the account holder should decide what access is appropriate, and the app should not be treated as proof that a shared family arrangement is officially supported.
Trust also changes between households. A couple with separate finances may want strict privacy even when they share rent. A parent may want to teach a teenager about spending but keep the card account private. Roommates may share a refrigerator and utility bills while having completely separate money. In all three cases, the app works best when the boundary is explicit: this is the cardholder’s account, and coordination happens around it rather than through uncontrolled access.
I would skip this approach for anyone who needs robust parental oversight, formal joint-account permissions, or a complete family budget in one place. The app’s value is strongest when the user wants direct management of a Walmart MoneyCard, not when the household needs a complex permission system. Choosing a tool that matches the relationship is more important than forcing every money task into the same application.
Everyday strengths and the friction I noticed
The strongest quality is focus. Instead of asking the user to learn a broad banking platform, the app centers the Walmart MoneyCard relationship. That can make routine checks feel less intimidating, especially for someone who mainly wants to know whether the card is ready for the next purchase. The free price also lowers the barrier to trying it, although a free app should not be confused with a complete financial service for every need.
The main limitation is the same focus that makes it approachable. If you want deep spending analysis, multiple-account aggregation, shared budgeting, or a detailed long-term financial plan, you will probably need another tool alongside it. I would not download this expecting it to replace a bank’s full mobile app or a dedicated budgeting platform. It is better understood as a practical control point for one card relationship.
Another point of friction is household interpretation. A person may see a balance and assume the money is available for general family use, even though the account belongs to one cardholder and may have personal obligations attached to it. The app cannot solve that communication problem. A short household agreement about who may request purchases, who records reimbursements, and who checks activity is just as important as the app itself.
The current version is 2.7.0, and the app has been available since March 12, 2025. I mention that because users should keep their expectations realistic: a relatively recent app experience may continue to change, and a version number alone does not tell you whether it includes every feature found in older or separate Green Dot products. I would judge it by the tasks you actually need rather than by assuming it has the maturity or breadth of a long-established bank platform.
How it compares with the usual alternatives
Compared with a traditional bank app, Walmart MoneyCard® feels more specialized. A bank application is usually the better choice when you need several account types, transfers across a broader banking relationship, or a complete view of checking and savings. This app is more appealing when the Walmart MoneyCard itself is the center of your everyday spending and you do not want unrelated banking features getting in the way.
Compared with a budgeting application, it serves a different purpose. Budgeting software is generally better for assigning categories, tracking several accounts, and planning household goals. The Walmart MoneyCard app is more direct for checking the card it manages. I would use the finance app for account awareness and a separate budget for decisions such as how much the household can spend on groceries this month.
Compared with managing the card through occasional web access or paper records, a mobile app is more convenient for a quick check before a purchase. That convenience is most valuable when spending happens away from home. However, convenience can encourage people to check less carefully, so I would still review activity deliberately rather than tapping through the app only when a transaction is declined or questioned.
For a shared household, the comparison is even clearer. A joint bank account or household budgeting service may be better when several adults need formal visibility and shared responsibility. Walmart MoneyCard® is better suited to a personal cardholder who participates in a household plan but does not need to turn the card login into a group account. That distinction should guide the download decision more than the app’s general finance label.
Who I would recommend it to
I would recommend it to a Walmart MoneyCard holder who wants a free mobile way to stay close to that card’s everyday activity. It is a sensible choice for someone who checks funds before errands, wants a more immediate routine than keeping receipts, and understands that card management is different from full financial planning.
I would also recommend it to households that can maintain clean account boundaries. One adult can manage the card, communicate the amount available for an agreed purchase, and keep reimbursements or shared bills in a separate system. That setup uses the app’s strengths without pretending it offers a shared family control center.
I would be more cautious for anyone who needs a complete picture of multiple accounts, formal controls for other users, or a detailed household budget. In those situations, a conventional bank app, a joint account, or dedicated budgeting software may be the better primary choice. The Walmart MoneyCard app can still have a supporting role, but I would not make it the only financial tool.
The app has an average rating of 3.7 from around 3.7 thousand ratings, with around 1.9 thousand written reviews, and it has passed 500 thousand installs. Those figures suggest a meaningful user base, but I would read them as context rather than a guarantee that every household will have the same experience. Finance apps are especially sensitive to account type, device setup, and personal expectations.
My household verdict
After looking at it through a shared-use lens, I see Walmart MoneyCard® as a useful personal finance companion with a clear but limited job. I like it for quick card awareness, pre-purchase checks, and a simple routine around everyday spending. I do not like the idea of using one signed-in phone as a communal household terminal, and I would not rely on it to coordinate every bill or represent everyone’s money.
My practical recommendation is to keep the account personal, keep the household plan separate, and use the app as the reliable checkpoint for the card itself. That approach gives the cardholder useful visibility while protecting privacy and reducing confusion about who is responsible for each transaction.
For the right user, the narrow focus is a benefit rather than a weakness. If your main need is managing a Walmart MoneyCard from an Android device running version 9 or later, the free app is worth considering. If your real need is joint financial control, family oversight, or full budgeting, I would choose a broader solution and use this app only where it genuinely adds convenience.
Walmart MoneyCard® FAQ
What is Walmart MoneyCard® and how does it work?
Walmart MoneyCard® is a reloadable prepaid debit card and mobile account designed for everyday spending. After setting up an account and verifying your identity, you can generally use the card for purchases wherever Mastercard or Visa debit cards are accepted, depending on the card version. The app lets you view your balance, review transactions, manage deposits, and control important account settings from your phone.
How can I add money to my Walmart MoneyCard® account?
There are several ways to fund a Walmart MoneyCard® account, although available options can depend on eligibility, location, and current program terms. Users may receive direct deposits, transfer money from an external bank account, deposit checks through supported features, or add cash at participating Walmart locations and other approved retailers. Fees, limits, processing times, and verification requirements should always be checked in the app before adding funds.
Does Walmart MoneyCard® charge monthly or transaction fees?
Walmart MoneyCard® may include monthly maintenance fees, cash reload fees, ATM fees, card replacement charges, or other service costs. Some users may qualify to have the monthly fee waived by meeting a qualifying direct-deposit requirement, but terms can change and may vary by account type. Before downloading or relying on the card, review the current fee schedule and account agreement carefully.
Is Walmart MoneyCard® safe to use for purchases and direct deposit?
Walmart MoneyCard® includes standard security tools such as account authentication, transaction monitoring, alerts, and the ability to lock or manage a card through the app. It can be useful for everyday purchases and receiving eligible direct deposits, but it is still important to protect your login details, enable available security features, and report suspicious activity quickly. As a prepaid account, protections and coverage may differ from those of a traditional bank account.
Can I use Walmart MoneyCard® internationally or withdraw cash from ATMs?
The card can generally be used for eligible purchases and cash withdrawals within the network and locations supported by its current terms. ATM access may involve withdrawal limits, operator charges, or fees from the card program. International use, foreign transactions, and availability outside the United States may be restricted or priced differently. Check the app’s fee information and cardholder agreement before traveling or planning a large withdrawal.













